
The information contained herein was prepared between mid-September and October 2026.
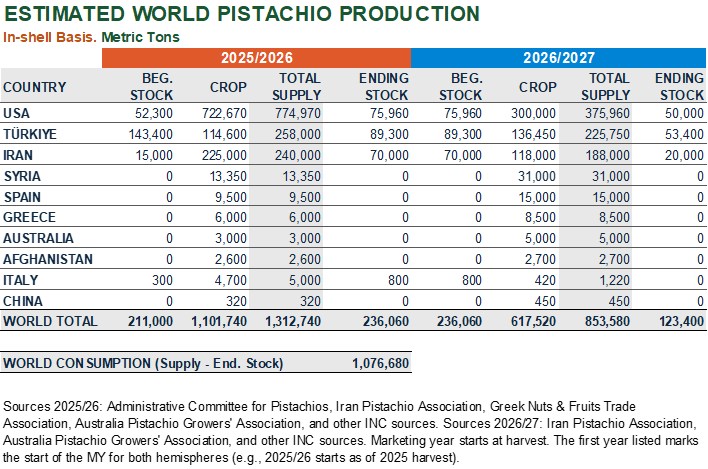
USA. At the end of crop year 2025, total US pistachio shipments reached 519,125 metric tons (1.14 billion pounds), up 22% from 426,000 MT (938 million lbs) shipped in 2024. Record shipments to Europe, the Middle East, and South America highlight continued strong global demand. Europe reached 154,500 MT (340 M lbs), up 23% from 126,000 MT (277 M lbs) in 2024. Middle East shipments rose 82% to 82,200 MT (181 M lbs), compared with 45,100 MT (99 M lbs) the previous year. South America recorded a record high of 4,000 MT (8.8 M lbs), 51% above the 2024 level of 2,650 MT (5.8 M lbs). Demand in Asia remained strong with shipments totaling 150,100 MT (331 M lbs), and domestic shipments steady at 108,000 MT (238 M lbs).
For the upcoming 2026 crop, significantly lower supply is expected due to a major cluster drop during a record heat wave in March. As a result, the upcoming 2026 crop is projected to have reached 300,000 MT (660 M lbs), which is a 59% decrease from the previous crop year.
Türkiye. Harvest has been in line with expectations, although it started 2–3 weeks later than usual.
Stable demand and reduced market appetite for expensive pistachio-based end products led to relatively stable prices during the harvest period in September. Although prices were reasonable for the domestic market compared with initial expectations, they remained significantly high for export markets. The anticipated larger new crop presents a promising opportunity for the second half of the marketing year.
Iran. As reported by the Iran Pistachio Association, monthly export shipments during the 12th marketing month (August 23–September 22) amounted to 9,000 MT in-shell equivalent. Despite available inventories, new offers were limited in anticipation of a smaller 2026 crop and continued depreciation of Iranian Rial. Conflict-related shipment challenges remained in place, while tighter supply continued to push prices higher. A good portion of the month’s shipments reflected previously committed sales.
Year-to-date exports reached 146,000 MT, down 28% from 2025. Including an estimated 24,000 MT of domestic consumption, total shipments amounted to 170,000 MT. The total shipment to opening-inventory ratio for the marketing year stood at 71%, resulting in the largest ending inventory (70,000 MT in-shell) on record. The decline in exports was largely anticipated given the various export impediments throughout the marketing year, including regional tensions, persistent logistical and operational challenges, and exchange rate fluctuations.
Kernels, green kernels and close-shells as raw material for kernels accounted for almost half of this year’s export shipments. Kernel demand continues to be the main driver for Iranian exports. The 2025/26 marketing year observed a continued growth in global kernel consumption, marking a historic record for Iranian pistachio kernels in terms of both volume and market diversification.
The pre‐harvest 2026 crop forecast stands at 118,000 MT of dried in-shell pistachios. The new crop is expected to consist of approximately 65% long varieties and 35% round varieties. IPA’s post-harvest estimate will be announced in November. As the 2026/27 marketing year begins, the global pistachio market is facing an unprecedented tight supply, elevated prices and considerable uncertainties. Iranian exporters continue to grapple with domestic regulatory challenges in addition to higher freight, insurance and logistical costs. Early indications from orchards in spring 2027 will shape market dynamics and price expectations for the second half of the marketing year.
Spain. The 2026 crop is forecasted at approximately 15,000 MT, 50% above initial expectations, despite being an off year. The increase is mainly attributed to newly established orchards entering production, with young plantations still relatively unaffected by alternate bearing. For the first time, their additional output appears to outweigh the alternate bearing decline in mature orchards.